Newsletters

IMSS temporarily restricts “Modalidad 40”
23 October 2026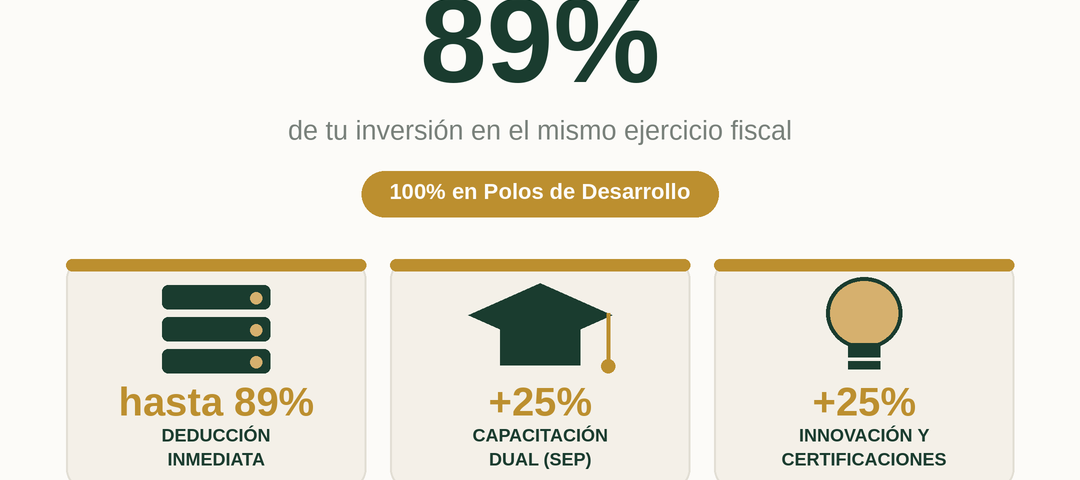
Immediate deduction of new assets, +25% for training and +25% for innovation (2025–2030)
Decree published in the Official Gazette (DOF) · January 21, 2025 · with a 2027–2030 continuity proposal in the Income Tax Law
The decree granting tax incentives to support the national strategy “Plan México,” published in Mexico’s Official Gazette (DOF) on January 21, 2025, offers high-impact benefits for companies investing in Mexico, with a clear focus on technology, nearshoring and innovation. The incentives apply to assets acquired from the decree’s entry into force through September 30, 2030.
What does it involve?
The scheme combines three incentives that can be used together to significantly reduce the income tax (ISR) of the year in which the investment is made:
1. Immediate deduction of new fixed assets — instead of depreciating the investment gradually over several years, a very high percentage is deducted in the same year the asset is acquired (for example, new servers and computer equipment).
2. Additional 25% deduction for training — an extra 25% benefit on the increase in training expense versus the average of the previous three fiscal years, under the Dual Education model with an agreement before the Ministry of Public Education (SEP).
3. Additional 25% deduction for innovation — an extra 25% on the increase in spending aimed at developing inventions (patents and utility models) or obtaining initial quality or export certifications.
How much can you deduct immediately?
The percentage depends on the type of asset or activity. Some of the most relevant for technology, manufacturing and industrial companies (2027–2030 scheme):
| Type of asset / activity | Deduction |
|---|---|
| Magnetic components and electronic boards for computing | 89% |
| Research and technology development in the country | 86% |
| Computers, servers, external storage and computer networks | 85% |
| Telephone switching equipment (non-electromechanical) | 83% |
| Electric, hybrid or hydrogen vehicles, cargo trucks and forklifts | 83% |
| Construction; agriculture, livestock, forestry and fishing | 83% |
| Machinery for chemical, petrochemical and pharmaceutical products | 65% |
| Generation, transmission and distribution of electricity | 49% |
Percentages under Article Two of the decree for the 2027–2030 period (approximate range 35%–89%). For 2025–2026 investments the rates are slightly higher (41%–91%). Within Development Hubs (Polos), the immediate deduction may reach 100%. Excluded, among others: office furniture and equipment, internal-combustion vehicles, armoring equipment and fixed assets that cannot be individually identified.
Development Hubs (Polos): up to 100%
If the investment is made within a “Polo de Desarrollo Económico para el Bienestar” (Development Hub), the immediate deduction can reach 100%. These hubs are strategic zones defined by the Federal Government to attract investment and nearshoring —mainly the Interoceanic Corridor of the Isthmus of Tehuantepec (Oaxaca and Veracruz), the Progreso I and Mérida I Industrial Hubs (Yucatán), and other Development and Circular-Economy Hubs. Important: the Polos decree incentives and the Plan México incentives cannot be applied jointly to the same investment; it is worth assessing which is more favorable.
Requirements and conditions
- Compliance certificate: issued by the Evaluation Committee (Ministry of Economy, a representative of the Advisory Council for Regional Economic Development and Relocation —with voice but no vote— and the Ministry of Finance (SHCP), which chairs it with a casting vote). Without it, the SAT system will not enable the incentive.
- Positive compliance opinion: being up to date under Article 32-D of the Federal Tax Code, with an active taxpayer ID (RFC) and an enabled Tax Mailbox.
- Holding period: keeping the asset in use for at least the two fiscal years immediately following the one in which it is deducted.
- CFDI support: supplier invoices must detail the new-asset status, serial numbers and project items; a specific record of the investments must be kept.
- Limited budget: the overall cap is MXN 30 billion (MXN 28.5 billion for immediate deduction and MXN 1.5 billion for training and innovation), with a minimum of MXN 1 billion reserved for companies with revenue of up to MXN 100 million. It should be managed well in advance.
The 2027–2030 horizon and the new deduction cap
The 2027 Economic Package proposes moving these benefits from the decrees into transitory provisions of the Income Tax Law, to provide multi-year legal certainty through 2030. As of this bulletin, the reform is still in the legislative process; if approved, it would take effect on January 1, 2027, while the current 2025 decree remains fully applicable.
A key point: the same 2027 reform introduces a cap on deductions for companies (the 96.67% / 99% mechanism). The good news is that investment and training incentives are excluded from that cap, so the Plan México immediate deduction stays protected; the cap applies to the rest of the deductions.
How we support you
- Investment (CAPEX) assessment: we plan your purchases of servers, infrastructure and equipment before year-end to maximize the immediate deduction.
- Filing before the Evaluation Committee: we assemble the technical file and manage the Compliance Certificate before the Ministry of Economy and the Ministry of Finance.
- Safeguarding requirements: we validate training agreements (SEP dual model) and the innovation/R&D support to protect the additional 25% against a potential SAT audit.
Planning to invest in equipment, technology or training? At García Accountants we assess your case and design the strategy so you make the most of these incentives. Let’s talk.
LR GARCÍA ACCOUNTANTS, S.C.
Zapopan, Jalisco · November 2026
This bulletin is for informational purposes only and does not constitute tax or legal advice for a specific case. Its application depends on the facts and circumstances of each company and on the current text of the decree and applicable tax provisions; we therefore recommend consulting us before making any decision.